

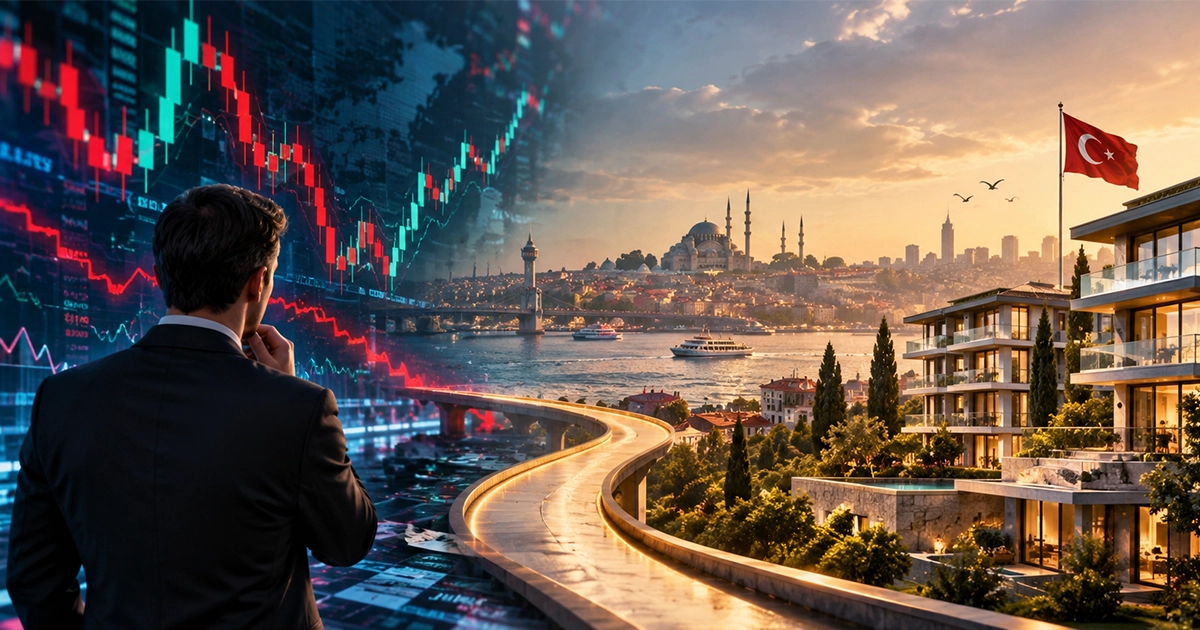
If we want to understand the reasons behind the current shock that has affected Türkiye’s financial markets, along with the sharp fluctuations in the stock market (BIST 100) and the liquidation of investment funds, there is no need to delve into complex economic equations. The story can simply be summarized by the gap between “virtual investment” on screens and “real investment” in tangible assets on the ground.
First: What Happened in the Stock Market and Investment Funds in Simple Terms?
Türkiye’s financial markets experienced a wave of declines and rapid liquidations, triggering panic among a broad segment of investors. What happened can be summarized through three main factors:
- Adjustments by the Capital Markets Board (SPK): The regulatory authority introduced new rules concerning the operation of investment funds and the free-float ratios of shares, with the aim of protecting the market and reorganizing it over the long term.
- A Series of Margin Calls: As thousands of investors redeemed their money from certain investment funds, brokerage firms and banks were forced to ask leveraged traders, who had purchased shares using borrowed funds, to provide immediate liquidity to cover their losses.
- Forced Liquidation: In order to obtain immediate cash, funds and investors rushed to sell their shares collectively and rapidly. This led to a temporary decline in market indices and triggered the “Devre Kesici” circuit-breaker mechanisms designed to protect the stock market.
The key point: The crisis was not caused by corporate bankruptcies or a decline in gross domestic product (GDP), but rather by a “technical and regulatory storm” concentrated within the world of financial screens and investment funds.
Second: Why Is Real Estate Becoming a “Safe Haven” in Türkiye?
During periods of turbulence in financial markets and equities, a fundamental investment principle comes back into focus: “Capital always seeks security before return.” This is where real estate stands out as one of the most stable forms of investment in the Turkish economy for several fundamental reasons:
- A tangible asset protected from margin-related volatility: Unlike stocks and funds, which can lose significant percentages of their value during a single trading session due to a “margin call,” real estate is a tangible asset that is not subject to forced liquidation and is not directly affected by traders’ momentary fear.
- A natural hedge against inflation: In Türkiye, real estate has historically been one of the most effective instruments for preserving purchasing power and capital. The market value of real estate assets increases, while rents adjust in parallel with inflation rates.
- The transition toward a monetary easing cycle: With the anticipated move by the Central Bank of the Republic of Türkiye toward lowering interest rates, returns on bank deposits are expected to decline. This could direct liquidity returning from the stock market and bank deposits toward real estate purchases in an effort to benefit from anticipated price increases.
Third: Comparative Summary of Investment Instruments
| Investment Instrument | Current Risk Profile | Level of Stability and Control | Expected Return in the Coming Period |
| Stock Market Shares and Investment Funds | Very High (Regulatory and margin-related volatility) | Low (Dependent on market movements and forced selling) | Volatile and requires expertise and daily analysis |
| Bank Deposits | Medium (Gradual decline with interest-rate cuts) | High in the short term / Declining in the future | Gradual decline with monetary policy easing |
| Real Estate Investment | Very Low (Stable tangible asset) | Full (Real estate ownership and real assets) | Sustainable capital growth + Continuous rental income |
Fourth: Future Outlook and Opportunities in the Real Estate Market
Successive financial crises demonstrate that the real economy, based on tangible assets, ultimately proves its resilience over the long term. The current withdrawal of liquidity from investment funds and the stock market does not necessarily represent a loss of capital, but rather a redirection of liquidity toward safer havens.
As the economic program enters the implementation phase, and as inflation levels and sovereign risks decline, Türkiye’s real estate sector—particularly in areas with strong investment potential and high tourism appeal—could enter a new phase of stable growth and price recovery. This makes purchasing and holding real estate assets at this stage a strategic approach to protecting wealth and achieving long-term financial balance.
By: Abdülaziz Al-Kashif

Join The Discussion